General liability
Discuss covered third-party injury and property-damage exposures, along with exclusions and contractual requirements.
Commercial insurance · Serving Indiana statewide
A new contract, employee, vehicle, or location changes the picture. Start with how your business actually operates, then discuss the coverage questions that follow.
Built around your real life
Lee Edwards works with business owners on commercial insurance needs. Share what you do, where you work, who relies on the business, and what an interruption would mean. The review can then focus on the exposures that are relevant to your operations.
Quotes from multiple insurance companies. Guidance for clients across Indiana. Available options depend on your needs and the insurer’s requirements.
Understand the building blocks
Use these topics to guide a review. Available products, limits, endorsements, and eligibility depend on the insurer and your situation.
Discuss covered third-party injury and property-damage exposures, along with exclusions and contractual requirements.
Review buildings, equipment, stock, valuation, limits, and the locations where property is used or stored.
A BOP can combine selected property, liability, and business income protections for eligible businesses. It is not an all-purpose policy.
Review vehicles used for business and questions about hired, rented, or employee-owned vehicles.
Ask about workers’ compensation, professional liability, cyber coverage, and other protections applicable to your activities.
Discuss what triggers coverage after an insured loss, waiting periods, restoration periods, and eligible ongoing expenses.
 Look at the details
A client or landlord may ask for a certificate, additional-insured status, or certain limits. Share the actual contract requirements with the agency. Do not assume a certificate creates coverage or that a standard policy satisfies every agreement.
Talk it through with the agencyPut the policy in context
These hypothetical examples show what to ask. They do not determine whether a claim would be covered.
Property repairs and lost operating income are different questions. A business income provision may depend on a qualifying cause of loss, a waiting period, a restoration period, and specific limits. A closure alone does not establish coverage.
Which event triggers business income coverage, and how is the period of recovery defined?
Give Lee the actual contract and insurance requirements. A certificate summarizes evidence of coverage; it does not itself add an additional insured, change an exclusion, or supply a missing policy.
Does my policy satisfy the requirement, or is an insurer-approved change needed?
Owned, rented, and employee-owned vehicles can create different exposures. Describe who drives, whose vehicle is used, and what the trip involves instead of assuming a personal auto policy or a BOP answers every question.
Which vehicle and liability coverage applies to the way we work?
Make the conversation count
You don’t need to arrive with every answer. These details can help the agency understand where you are starting.
Operations, locations, revenue and payroll information
Current policies, renewal dates, vehicles, and equipment
Contracts or insurance requirements you need to discuss
Use the agency’s requested secure process for sensitive application information. Please do not email Social Security numbers or medical records.
A little clarity before we talk
Understand the details before you decide.
Lee Edwards is the agency’s commercial insurance contact. Email lee@nauyokasins.com or call 317-660-1710 to discuss the business and arrange the right conversation.
No. A business owners policy combines selected protections for eligible businesses, but commercial auto, workers’ compensation, professional liability, cyber risks, or other needs may require separate coverage.
Do not assume it does. Business equipment, customers visiting the home, products, and professional work can create different exposures. Describe the activities and ask what your home policy excludes or limits.
Share the insurance provisions with the agency so applicable limits and endorsements can be discussed. Legal interpretation and other contractual obligations should be reviewed with your legal adviser.
See the bigger picture
Your next question may connect to another part of your coverage.
Think about how your policies work together.
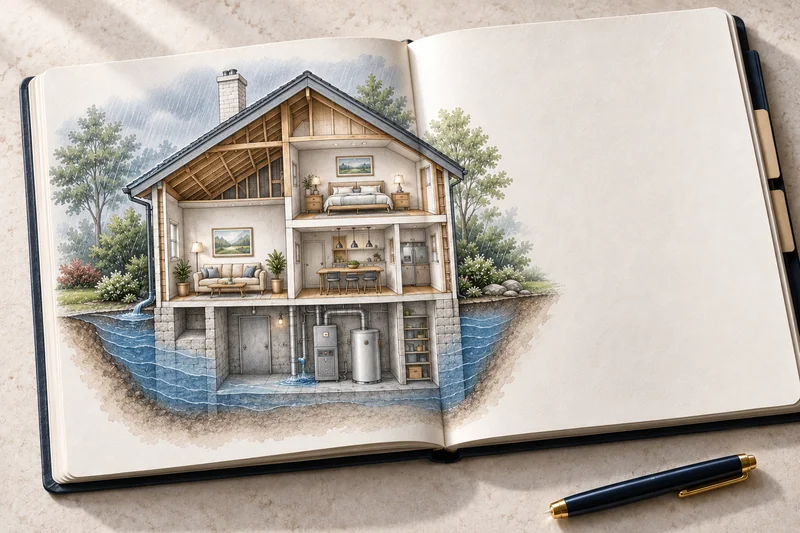
Start before water is at the door.
Based in Carmel. Serving all of Indiana.
Bring your current policies and your questions. We’ll help compare available quotes from multiple insurance companies and put the details in context.